Wednesday, July 22, 2020

Finance 201: What is the 3-Fund Portfolio?

Hi friends,

Remember when I talked about the inventor of the first index fund - John Bogle? He has a fan club, known as the Bogleheads, a group of superfans of him. They have created this portfolio that is in line with John Bogle's approach to investing; Low-cost, tax-efficient, and diversification.

The portfolio only consists of 2 types of assets, made up of 3 funds (which explains the name of the portfolio). The 2 assets are just stocks and bonds - as what John Bogle has outlined in one of his books (The little book of common sense investing).

The funds are as the following:

1. US stock index fund (either the large-cap or the total US market)
2. International stock index fund (excluding the US, so that you do not double invest)
3. US bond index fund

Yes. I was really surprised by the simplicity offered by this portfolio. In his book, John Bogle iterated on his belief in US enterprises (especially about the long-term returns of the US is around 7% after inflation). But he emphasized that there is a need for diversification in other countries' economies and enterprises as a hedge that other countries have a higher growth potential compared to the US (as it is a developed country). 

Now that we have a clear idea of the portfolio, let's take a look at the allocation. #Do note that there isn't a one-size-fits-all approach for this portfolio. you are expected to increase or decrease your volatility in accordance with your financial circumstances. John Bogle himself has recommended for bond weightage to increase as you age. 

For the example used in my blog, I will be using an example of a 24 years old male (I got the allocation from the Vanguard questionnaire).

3-fund portfolio allocation:
  • Total US Stock market index fund/etf - 60% (VOO, VTI. So long as it is low-cost around 0.15% expense ratio)
  • International Stock market index fund/etf - 20% (VXUS, ACWS. It must include developed and emerging markets, excluding the US. Remember LOW EXPENSE)
  • US Treasury bonds/US Investment-grade corporate bonds - 20% (VGLT, ITE or LQD. You can choose treasury bonds for the safer aspect or high-grade corporate bonds for slightly higher risk. I would choose treasury bonds)

Comments:

For my personal portfolio, I would stick to the asset prescribed here, but I would prefer long-term treasury bonds (VGLT). This is as I would prefer the non-volatile portion of my portfolio to be even more stable when the rest of the portfolio is going everywhere. Also, you can see that by using this portfolio, you can essentially pivot between the US and other parts of the world's companies (so you can decide how you want to focus your portfolio)

So yes, under the adaptation to Singapore section, I will talk about how I plan to incorporate this into my personal portfolio (*hint* CPF *hint*)

Backtest of 3-fund portfolio (Jan 1997 - May 2020):
Portfolio 1: 20% Bonds + 20% US Stocks + 60% International Stocks
Portfolio 2: 20% Bonds + 40% US Stocks + 40% International Stocks
Portfolio 3: 20% Bonds + 60% US Stocks + 20% International Stocks


So... unsurprisingly, the US-centric portfolio has a higher Sharpe ratio compared to the rest. But it does not mean that it will be the same going forward (that's why there is a need to diversify) 


The graph shows the same too (That's why John Bogle has said too: Do not bet against American enterprises. But yes, he also said to allow for other markets with higher growth potential in our portfolio.)

Rolling returns (For a long holding period, what will happen to our money):
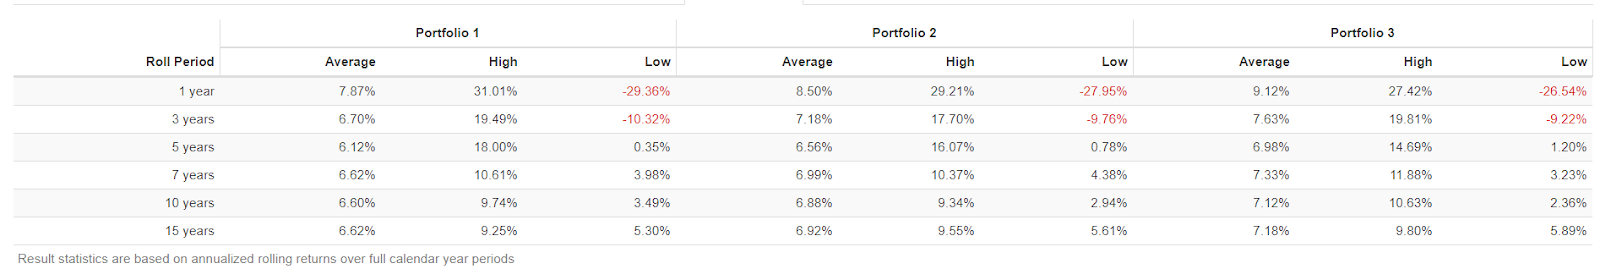
As expected, the longer the holding period, the more consistent the returns across different time periods. 

Do let me know if you are interested in the pdf for the results and I will email it to you, I can't seem to upload it onto this platform.

Adaptation to Singapore:

Alright! This is the important part that you guys are here to see. You love the 3-fund portfolio and you want to apply it. This is how I plan to apply it for the Singapore context and you might want to apply that for your own portfolio. 

As you know, we have something known as CPF in Singapore. This is really important as we are required to contribute around 20% of our salary to it in the working portion of our lives. It also gives a 4% interest rate (I'm only calculating SA) annually So my plan is to substitute the bond portion of the portfolio with CPF and use invest the rest of my money to the S&P 500 and the International market. 

This will be a rough estimation of my portfolio at age 40:

  • Stocks (69.06%)
  • Bonds (CPF - 30.94%)
Total = S$1.1 Million.

Conclusion:
As always, this is my plan for my personal portfolio. Hence, you should tailor it to your personal situation. But yes, even though John Bogle has created index funds 50 years ago, they are more relevant than ever today.


With that, 
I end today's topic. 

Stay vested, Stay frugal my friends,

Dionysius

Source:
https://www.bogleheads.org/wiki/Three-fund_portfolio
https://personal.vanguard.com/us/FundsInvQuestionnaire

Saturday, July 18, 2020

Mid-July Update

Hi friends, 

I hope that this blog post finds you well and that you have continued to stay frugal and stay vested as the market continues to be volatile. I have been a bit caught up with my internship, side hustles, and my FYP - Which explains for the delay in my mid-month updates. 

But yes, I am only left with 3 weeks of my internship, but I can anticipate that my commitment to this blog post would be further challenged as school is going to start (and my side-hustle of tuition is increasing in demand as the year is heading to an end). Rest assured, I will definitely continue with my mid-month updates and my start-of-month updates even if I stop writing about the financial books that I have read. 

Now, let us talk about the things that have happened:

1. Tesla's potential entrance into the S&P 500:

There has been another round of speculations about Tesla being added into the S&P 500 again (since it became the most valuable car company). Furthermore, if Tesla is included in the S&P 500, it would account for 0.8% of the market. WOW.  But Tesla would have to fulfill 1 more criterion: A) Posting a profit in the second quarter of 2020 (As the sum of the previous 4 quarters' net income must be positive, with the latest quarter being positive as well)

If Tesla is included in the S&P 500, it may mean a 3-5% increase in the stock price as the index funds would be required to put the stocks into its portfolio (driving up demands and price). Thus, if you are already holding on to the stock, please do not sell. 

But do note that I am not advocating for you to buy into the stock with your live-savings. You have to take note of one important situation - What if Tesla isn't added into the index? Considering that the price of Tesla is so high right now (because of the possibility of inclusion), I would expect the price to fall if Tesla cannot enter the index as investors are disappointed. 

2. Market trading side-ways for a month:

From the 8th of June 2020 to 15 July 2020, the market dropped by 0.18% (With volatility along the way of course). So yes, the market is effectively trading sideways for a month now. Whether or not it will continue to happen for the foreseeable future - I do not know. But I know the best strategy for this situation. Dollar-cost-averaging - Slowing investing your cash into the market regardless of how the market is doing. 

That is the approach that I am doing right now and it will be how I will do it for the rest of my life. heh. 

3. Economies closing up again:

I believe that you definitely read it in the news about the states in the US/ countries in Europe that have to begin closing up due to the increase of Covid-19 cases when the economy opened up. This would mean that circuit breaker 2.0 might happen. 

What this might lead to is that we might have another bear market for the stock market (which is something that I am looking forward to). So yes, let it fall, and I will deploy my money like never before. Heh. 

Here are some of the changes ton my investments from the following news:

1. Continue to DCA, but moving into platforms which allows fractional ownership (StashAway)

2. Putting more effort into my side-hustle (for more cash reserves to deploy if another downturn is to happen)

With that, 

I hope that you will be reminded that buying stocks is like buying your groceries - YOU BUY MORE when the price drop. Not when the price increases.

Stay vested, Stay frugal my friends,
Dionysius

Wednesday, July 15, 2020

Books by the Giants: The Intelligient Investor


Hi friends,

Let me start off today with a story:

Imagine you bought a house, worth $300,000. You have a neighbor, Mr. Market, who comes by every day. Each time he comes, he will quote you a price on your house. Some days, he is in a good mood, he quotes you $500,000. Others, he is a bit moody and quotes you $100,000.

When you hear his quotations, will you sell your house just because he quotes you a price way lower than what you bought your house at? If the answer is NO, why are we selling when we see our stock prices fall?

This is the mindset that Benjamin Graham is trying to convey in his book - The Intelligent Investor. An intelligent investor does not let the market define the values of his portfolio. Some facts about Benjamin Graham, he was the mentor of Warren Buffett, he is known as the creator of value- investing. The Intelligent Investor was also commented by Warren Buffett to be "The best book written on investing, ever!" Let me start off by going straight into my thoughts and comments about the book.


Thoughts and comments:

This book isn't an easy read. definitely. But I felt that the book is significantly harder in the beginning chapters. But with the help of the commentaries, it eased the difficulties in trying to understand what Benjamin Graham was trying to convey. Also, this book does not have much calculation/formulas. It serves more like a principle-based approach to value-investing along with some guidelines that we can follow to filter out companies that have a better chance of delivering better value.

I felt that, after reading this book, I have a better understanding of what a stock is, and what are the expectations if I were to be an active investor. Therefore, I have decided that I am going to be a passive investor, with a small amount of my money (5%) invested in speculative assets as part of my "fun money"

Let's move on to the 6 principles that I have derived from the book:

1. A stock is a business, not a ticker symbol or lines in a chart:

When we want to buy a stock, we should evaluate it from the POV of a business owner. How much money would you pay to own a business that isn't profitable? How much money are you willing to pay for a business with sustained profit growth of 8% every year?

Hence, it is important for us, as an intelligent investor, to view stocks as ownership of businesses, with the objective of producing and sustaining as much profit as possible. Since we are partial owners of this business, we should expect to benefit from this growth in business.

2. A great business can be either a good buy or a bad buy at a certain price:

Stocks with a high PE (price to earnings ratio) tend to do worse than their counterparts. Hence, even a good company (like Coke, Raytheon, General Electric) would be a bad buy when you buy into it at a high PE ratio (>25).

What this means for us is that there isn't any point in trying to copy the portfolio of successful investors. This is as the price that he bought his portfolio (his entry price) is significantly different from yours. Hence, both of your returns would be significantly different.

3. Crises are great for the intelligent investor:

In a typical bull market scenario, it would be hard to find undervalued stocks. This is even worse in the ending period of the bull market, there would be a lot of bad quality new issues out in the market. 

However, when there is a crisis, fear would be the one ruling the market. There would be a lot of pessimism too. Hence, great companies' stock prices would also be affected negatively, these great companies which are previously too expensive would become a bargain. But the important thing is: You need to learn how to determine great companies, also you need the guts to do the opposite of what everyone is doing. 

4. Businesses can swing from being undervalued to widely overvalued:

Throughout history, there are phases where certain industries are favored (Right now, it is the technological companies, previously it was the internet companies, even further back was the conglomerates). Hence, when certain industries are favored, they would highly be overvalued. In these times, there would be companies of neglected industries that are undervalued and would be a good bargain. 

5. Passive (or Defensive) investors have a radically different investing approach compared to Active (or Enterprising) investors:

The main difference between the passive and the active investor is the amount of time, effort, the energy that both parties are willing to put into analysing stocks and bonds. 

For the defensive investor:
It would be better for him to invest in a market index fund (US) and diversify using index funds of other countries (Emerging Markets) and bond funds (US Treasury). He would invest it by DCA-ing into his portfolio and rebalance on an annual basis. 

For the enterprising investor:

As he is expected to put in significantly more effort and time in analysing stocks and bonds compared to the defensive investor. He will attempt to beat the market's return through the careful selection of stocks. 

He should think of his actions as a business (similar to a mutual fund) and manage his returns as such. This would mean that he would be doing it full-time, with an expected salary and all that. The approach of the enterprising investor will be elaborated in the next point.

6. The enterprising investor has a lot of things to do:

The enterprising investor should treat what he is doing as a full-time business that deals with investment. For every stock that he looks at, there will be an entry price, exit strategy, and participation strategy. His portfolio should also not consist of more than 30 stocks

Here is a rough run-through of how the enterprising investor can arrive at his 30 stocks:

a. From a list of all the stocks in that market, filter out using 6 criteria (read the book if you are interested). You should expect to find about 40-50 stocks. 

b. From the 40-50 stocks, further, filter it by an additional set of criteria that is defined as important by the investor. 

c. This should filter to 20-30 stocks. This is where the fun part begins, the enterprising investor would then read the annual reports of these companies for the past 5 years and look for red-flags in the companies' reports. Benjamin Graham gave a few examples of the red-flags (They can be frequent changes of management teams, recurring special payments, etc)

d. From these, he will choose around 4-5 stocks that he is satisfied with (especially those with a moat against its competitors) and buy it. 

THAT'S NOT ALL. THAT'S FOR THE ENTRANCE INTO THE STOCKS. There is still the exit and participation strategy. 

Exit Strategy:

The enterprising investor should cash out when there is a change in the quality of the management team or when the objective of the managers no longer aligns with the investors. The enterprising investor can also exit when the stock price goes into the speculative regions (high PE ratio) and this would produce a decent returns

Participation Strategy:

For this portion, Benjamin Graham recommended to actively look at the yearly distributions of the company to gauge the effectiveness of the managers. The managers should serve to increase shareholder returns. This can be done through participation in AGMs.

From these principles, I have decided that I am going to be a passive investor as I do not plan to have invested as a full-time career, But if you do, here are some of the action plans that you can do:

1. Learn about the rationales and exact figures on how to do stock evaluations (Can be found in the book. I did not include it as it will be too technical).

2. Treat investing as a real business that you are doing for 1-2 years, take note of your mentality, and some of the emotional pitfalls that you can make mistakes in.  

3. Measure your returns against the market index. If you do well, then MAYBE, you can do it full time. 

Conclusion:
I can understand why Warren Buffett had such high praise for this book. If you are familiar with Buffett's investing approach, it is highly similar to Benjamin Graham. Especially in terms of treating stocks for the things that they truly are: Ownership of a business and that there is a price that we should be willing to pay for. I hope to read this book again soon as I truly feel that I have not understood everything about the book. 

Whether or not I will be an active investor, maybe I will do it with my fun money in the future. But for now, no. 

Till then,
Stay vested, stay frugal my friends, 

Dionysius

Source:
The Intelligent Investor

Saturday, July 11, 2020

Investor Spotlight: Benjamin Graham

Hi friends, 

In the previous entry of this series, I have talked about Warren Buffett - The most famous investor on earth. But what if I tell you that he had a teacher/mentor that shaped his investing approach? If Warren Buffett is the person who mastered value investing as an investment approach, this man is the father of value investing. Yes, I am talking about Benjamin Graham today.

Just a quick explanation of what is value investing; 

It is essentially by taking into consideration the financial health of a company (balance sheets, dividends, assets), we can calculate out the intrinsic value of the company. From there, if the market price is lower than the calculated intrinsic value, it would be a good buy (undervalued).

Now, let me move onto him, his life and everything about him

1. Background

Benjamin Graham was born in 1894 in the UK, but he moved to the US after that. He attended Columbia University and graduated 2nd in his class in 1914 (he was 20). He declined an offer by the school to teach and moved onto Wall Street as a runner for stocks and checks. 

He then started to analyze companies on his own and became a full partner in the company he worked in subsequently. His annual income was US$500,000 at one point in time, with a substantial amount of investment. This was when things took a turn for the worse. 

In 1928, he started teaching investment classes in Columbia. In 1929 (he was 35), the stock market crashed and the great depression happened which caused him to lose most of his money. However, it is also because of this that led him to develop his own way of investing. He released his first book - Security Analysis in 1934 (he was 40) and his second book, and one that is more famous, - The Intelligent Investor in 1949 (he was 45). Those books then taught generations of investors after him on the principles and actual method of value investing. 

In 1951 (he was 47), Benjamin Graham met the student that will make his investment method more famous than ever before - Warren Buffett. And I guess the rest was history. He then died in 1976 (he was 82).

Oh, his greatest gain was from GEICO, when he bought 50% of it in 1948 for $712,000 and it grew to $400 million in 1972. 

2. Investment Approach

I believe that his investment approach is highly influenced by the great depression, which is partially caused by speculations. Hence, he would want a way to look at stocks in a more quantifiable way. He views investing as partial ownership of a business and we should not let the market determine the value of the stock that we buy. Hence we should focus on the business' performance and not the market value. 

Hence, by focusing on undervalued stocks, 2 things can be achieved:

1) The margin of Safety (as the stock would have assets for liquidation in the event of bankruptcy) 
2) More Room for growth (stocks with a low PE ratio have a higher room for growth)

Here are some of the things that he looks out for in a stock:

1. Debt to current asset ratio (<1.1)
2. Current ratio - Current asset / Current liabilities (>1.5)
3. Positive Earnings per share growth (for the past 5 years)
4. Price to earnings ratio - Price/earnings (<9)
5. Price to book ratio - Price/book value (<1.2)
6. Dividends - (healthy and sustainable, for the long wait for the undervalued stock to be correctly priced)

There are other things that Benjamin Graham looks out for but if I were to list them all out, there will be no end. According to Warren Buffett, his teacher's way of investing is really safe, and that if someone follows his advice and principles, they would not lose money.  


3. Broader Impact on Industry

Benjamin Graham's investment method - Value investing is still being utilised and taught today, 50 years after his death. Hence, there no doubt that he is an impactful figure in the investment world. But I guess there are 3 fields that I would like to highlight:

a) Value investing 

With his two books, Benjamin Graham has taught us the principles of value investing and made a fundamental distinction between investing and speculating. He has also focused on the psychological approach that we should have when it comes to investing - That our decisions should not be dictated by the movement of the market and that we should only buy stocks that we fully understand. 

b) Value investing disciples

Several of his students/disciples have become successful in their ways. Some continued to practise the methods he laid out, while others built upon it. They are Warren Buffett, Irving Kahn, Charles Brandes, Walter J. Schloss. 

Even though he is dead, his legacy lives on in the students who still practise his methods today. 

c) Securities Act of 1933

He helped in the crafting of the landmark legislation of the securities act of 1933. This would require companies to provide financial statements that have been audited by independent accountants. This was significant as Benjamin was against the use of creative accounting to mask the actual financial condition of the company,

4. Personal Impact

As of writing this post, I have read once through The Intelligent Investor - I felt that it gave me a better understanding of what stocks stand for. His principle of not allowing markets to determine the value of my investment for me is also important. 

Do I want to be an active value investor? No, sorry.... I do not have the time. I would rather do index investing (which is also recommended by Graham) and use the time saved to write this blog to teach people about finance. 

5. Fun Fact
  • His annual returns were 20+%
  • He never used the phrase - Value investing, it is a term used to describe his way of investing
  • Value investing has evolved significantly to include technology stocks or industries where book value would not be useful. 
Conclusion:

Benjamin Graham is still and will always be influential with his method of value investing. His principles will always be relevant, and I find his investments even more useful now when there is much pessimism in the market. We should never let the market dictate the value of our investment. I hope that this article was educational to you. 

Till next time, 
Stay vested, stay frugal my friends

Dionysius

Sources: